Save 30% by using your HSA or FSA card
Your card is a payment option at checkout, next to credit card and the wallets.
How paying with HSA or FSA saves you 30%
These accounts exist for one thing: paying with pre-tax money for what treats, eases or prevents a condition a provider has diagnosed.
One hundred dollars of pay, two ways. From your bank account: you earn $100, $30 goes to taxes, $70 is left to spend. From your HSA or FSA: you earn $100, no taxes, $100 is left to spend.
Illustrative math, not tax advice and not a discount. Your savings depend on your own tax rates and your plan.
Try your own numbers
Federal, state and payroll tax combined.
Tax you never pay
$2,475.00
on a $8,250.00 order paid with pre-tax dollars at 30%
What happens at checkout
Three steps, all of them inside the checkout you already use.
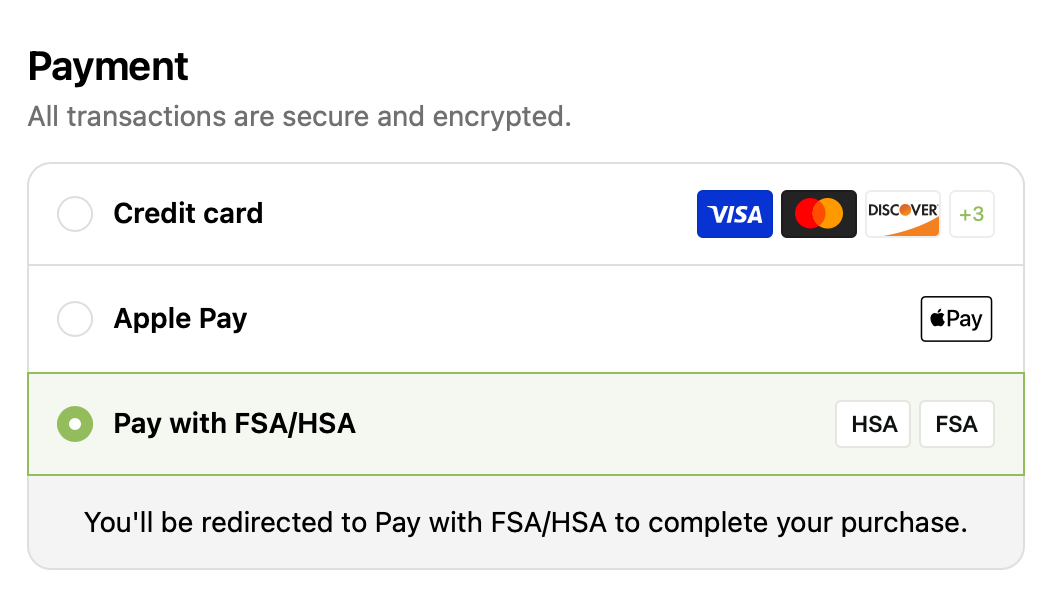
Pick HSA/FSA in the payment list
It sits with credit card and the wallets, not off in a separate flow.
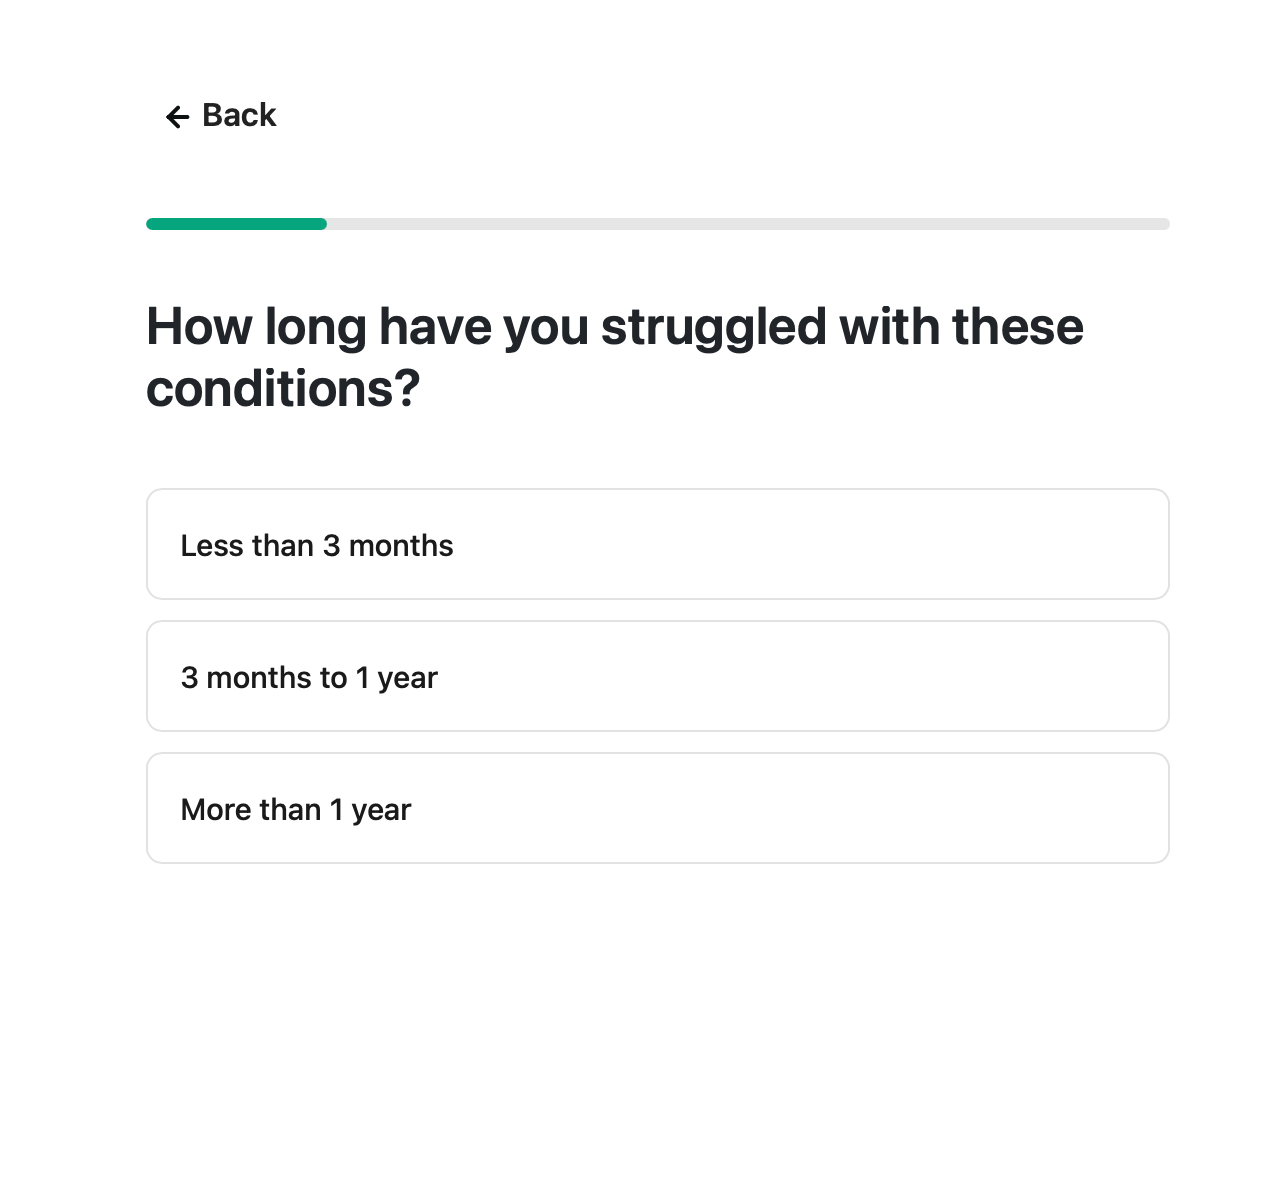
Answer a few health questions
A licensed provider reviews your answers, not our products.
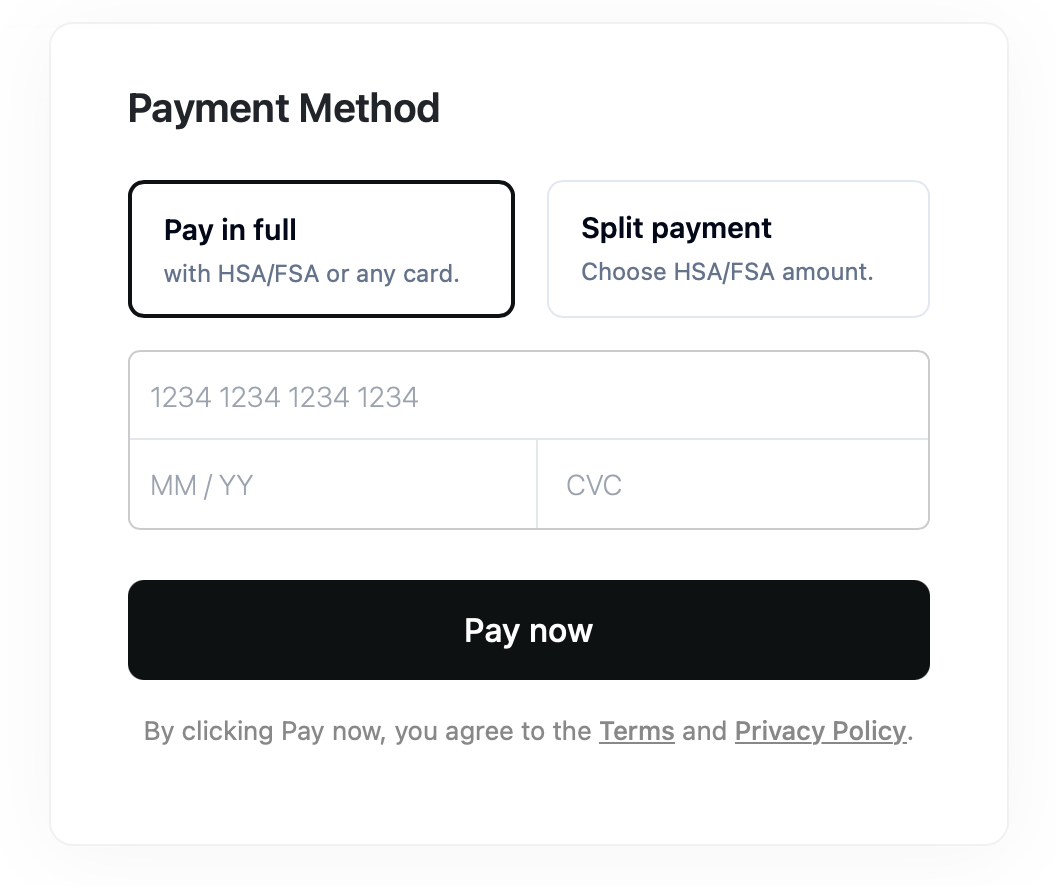
Pay with your HSA or FSA card
Use your HSA or FSA card, or split the order across two cards.
Shop HSA eligible items
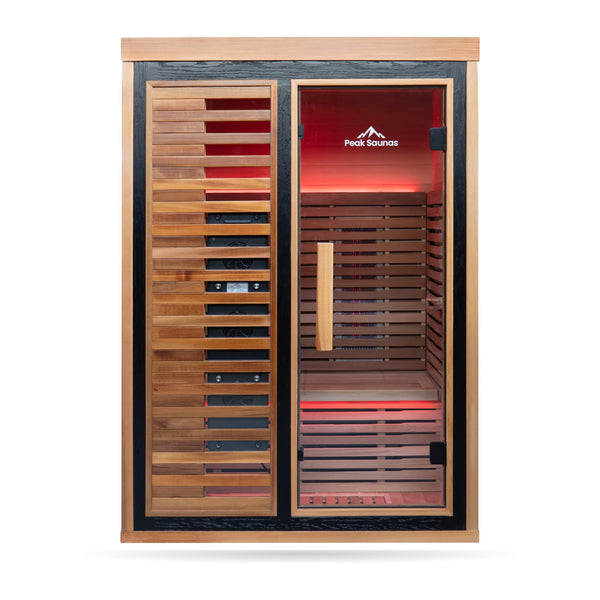 HSA eligiblePeak Fuji 2-Person Full Spectrum Infrared Sauna$8,250.00
$14,032.00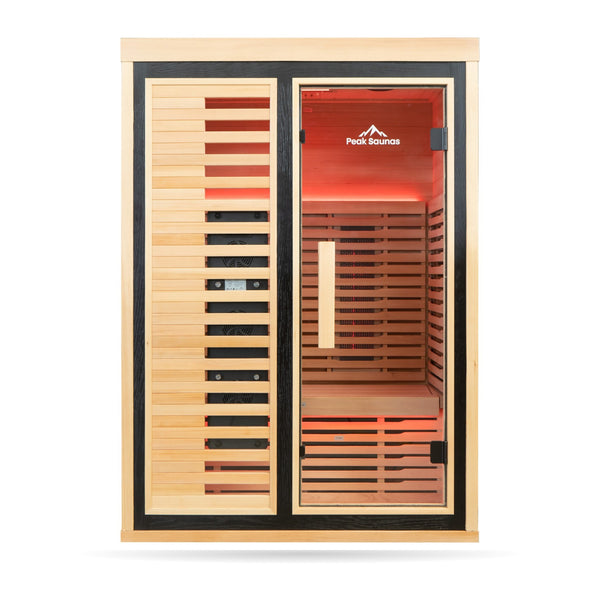 HSA eligiblePeak Everest 2-Person Full Spectrum Infrared Sauna$7,950.00
$13,532.00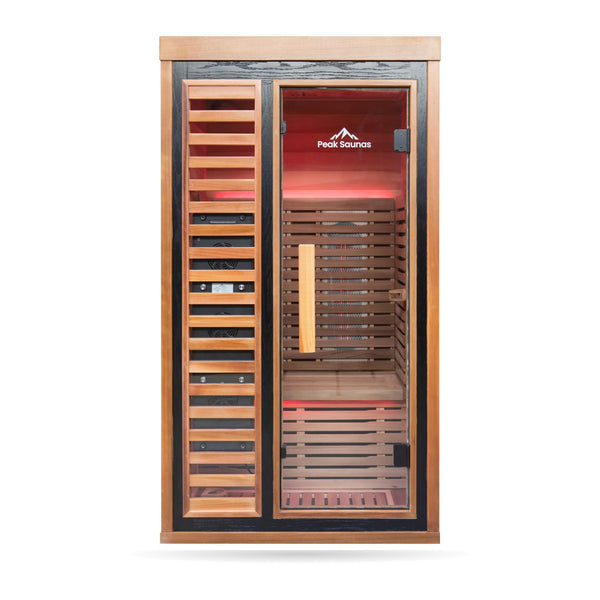 HSA eligiblePeak Rainier 1-Person Full Spectrum Infrared Sauna$7,250.00
$13,032.00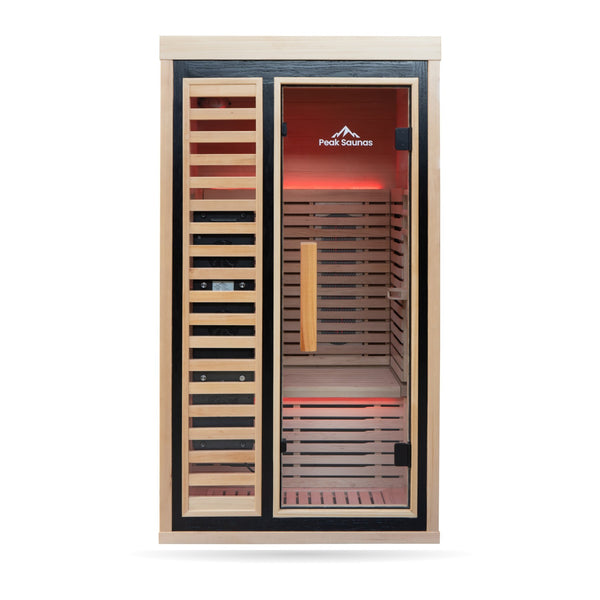 HSA eligiblePeak Shasta 1-Person Full Spectrum Infrared Sauna$6,950.00
$12,532.00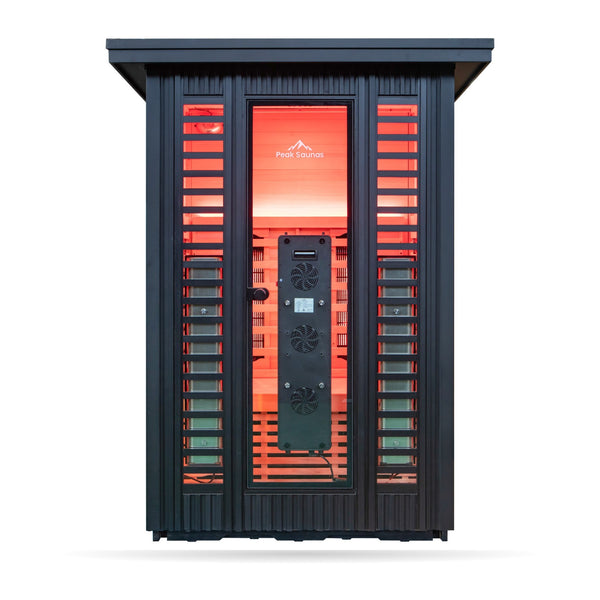 HSA eligiblePeak Patagonia 2-Person Outdoor Full Spectrum Infrared Sauna$10,950.00
$18,032.00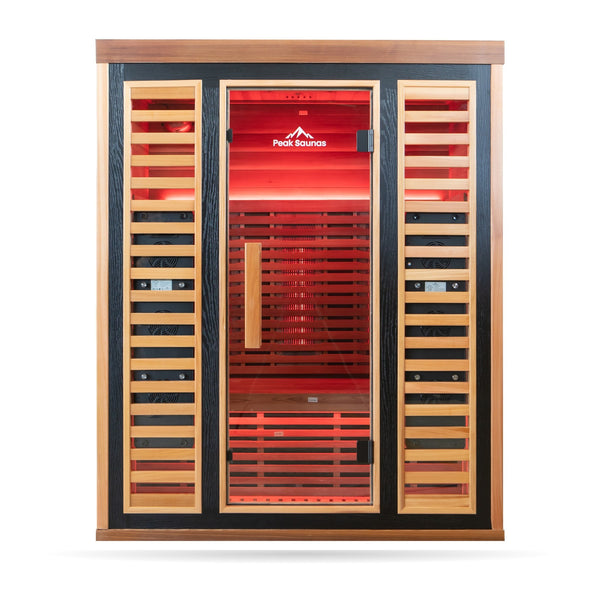 HSA eligiblePeak Matterhorn 3-Person Full Spectrum Infrared Sauna$10,950.00
$19,831.00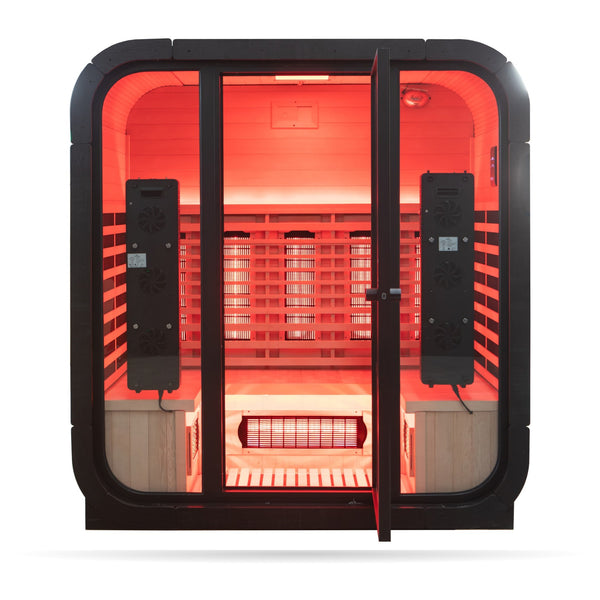 HSA eligiblePeak El Capitan 4-Person Outdoor Full Spectrum Infrared Sauna$16,750.00
$25,831.00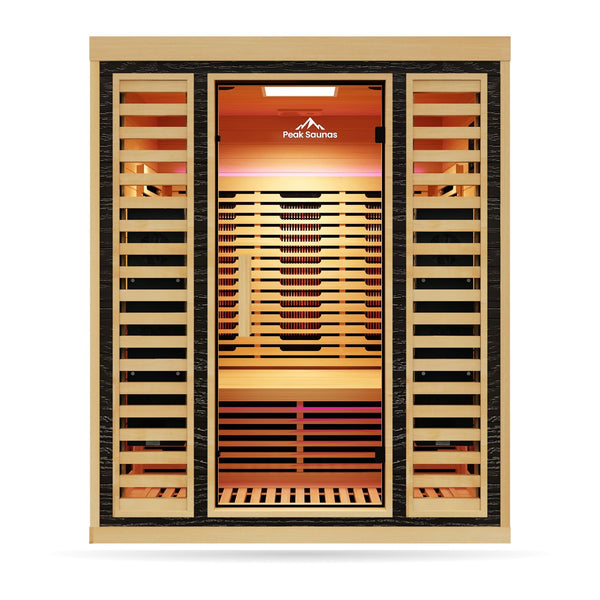 HSA eligiblePeak Denali 3-Person Full Spectrum Infrared Sauna$9,750.00
$18,831.00 HSA eligiblePeak Kilimanjaro 5-Person Outdoor Full Spectrum Infrared Sauna$15,450.00
$20,032.00 HSA eligiblePeak Mini 1-Person Full Spectrum Infrared Sauna$5,450.00
$10,832.00 HSA eligiblePeak Crown 2-Person Full Spectrum Infrared Sauna$5,450.00
$9,237.00
Questions before you buy? Talk to us.
Before you worry about it
No new account
No new account to open and no balance to top up. Bring the card your employer gave you.
Your order is not held up
The questions do not hold up your order, so you pay and check out as normal.
A provider reviews you, not us
A licensed provider reviews your answers, not our products.
Normal cards still work
Credit card is still a payment option at checkout, alongside the wallets, and nothing about this page changes that.
Common questions
What are FSA and HSA accounts?
Both let you set aside money from your paycheck before taxes for eligible health expenses. An HSA is a health savings account and generally stays with you year after year. An FSA is a flexible spending account and usually has a yearly deadline. Not sure if you have one? Check with your employer or your benefits provider.
Can I use my HSA/FSA at Peak?
Yes. Pick HSA/FSA in the payment list at checkout, answer a few quick health questions, and pay with your HSA or FSA card the same way you would use any other card. If your order needs a letter of medical necessity, it comes to you by email after you check out.
Can I use my regular credit card instead?
Yes. Every regular payment option is still there. You can also split an order: put part of it on your HSA or FSA card and the rest on a regular credit or debit card.
What is a letter of medical necessity?
Under IRS rules, some things you buy count as a medical expense only when they treat a specific health condition, not when they are for general health. A letter of medical necessity is a licensed provider's written opinion that a product may treat a condition you have.
Here is how it works. You answer a few health questions at checkout. A licensed provider reviews your answers, not our products. The questions do not hold up your order, so you pay and check out as normal. Your letter arrives by email after you check out. Keep it, because your plan may ask to see it. Not everyone qualifies, and your plan makes the final decision on any claim.
Are there any fees?
You pay the price on the product page. There is no extra charge at checkout for paying with your HSA or FSA card.
When should I use my FSA/HSA dollars?
Any time of year. HSA money generally stays with you year after year. FSA money usually has a deadline, and many plans run use it or lose it at the end of the year, so check your plan's dates before December.
How long until I get my letter of medical necessity?
It arrives by email after you check out. If you do not see it, check your spam folder first, then reach out to us through our contact page and we will help.
I don't have an HSA/FSA. Can I still benefit?
You need one of those accounts to use pre-tax money. Many employers offer them during open enrollment, so it is worth asking. You can still check out normally with any card.
I don't live in the US. Can I still use this?
HSA and FSA are United States programs, so the pre-tax option only applies to US accounts. Everything on the site can still be bought the normal way.
The fine print
Some of what we sell may qualify as a medical expense under IRS rules, and some items need a letter of medical necessity, which is a written opinion from a licensed provider that a product may treat a specific condition you have. That review is done by a licensed provider through an independent partner, not by Peak. Not everyone qualifies. No product on this site has been reviewed or approved for you in advance.
A letter is not a guarantee that your plan will pay. Your plan administrator, the company that runs your HSA or FSA, makes that decision, and plans differ.
Peak is not a tax advisor, medical provider or benefits administrator, and nothing here is tax, legal or medical advice. Ask your plan administrator about your account or a claim, and a tax professional about taxes.
There is a yearly cap on how much you can put into one of these accounts. The IRS publishes the current numbers in Publication 969.
